A new foreign subsidiary passes to a local accountant the day it goes live, and that feels like diligence. You have just delegated the obligations most likely to dissolve the entity to the one professional whose domestic practice has never required filing them.
These obligations exist precisely because the owner is foreign, which is the same reason a single-market firm has never learned them – a Canadian notification can sit unfiled for years while a monthly invoice reading only ‘corporate compliance’ keeps clearing. You are paying for the feeling that someone is watching, which is a separate product from the work.
None of this announces itself as a cost. An annual return that should have cost nothing surfaces instead as a forced statutory audit, because the warning letters went to a serviced desk you surrendered two leases ago.
Key Takeaways
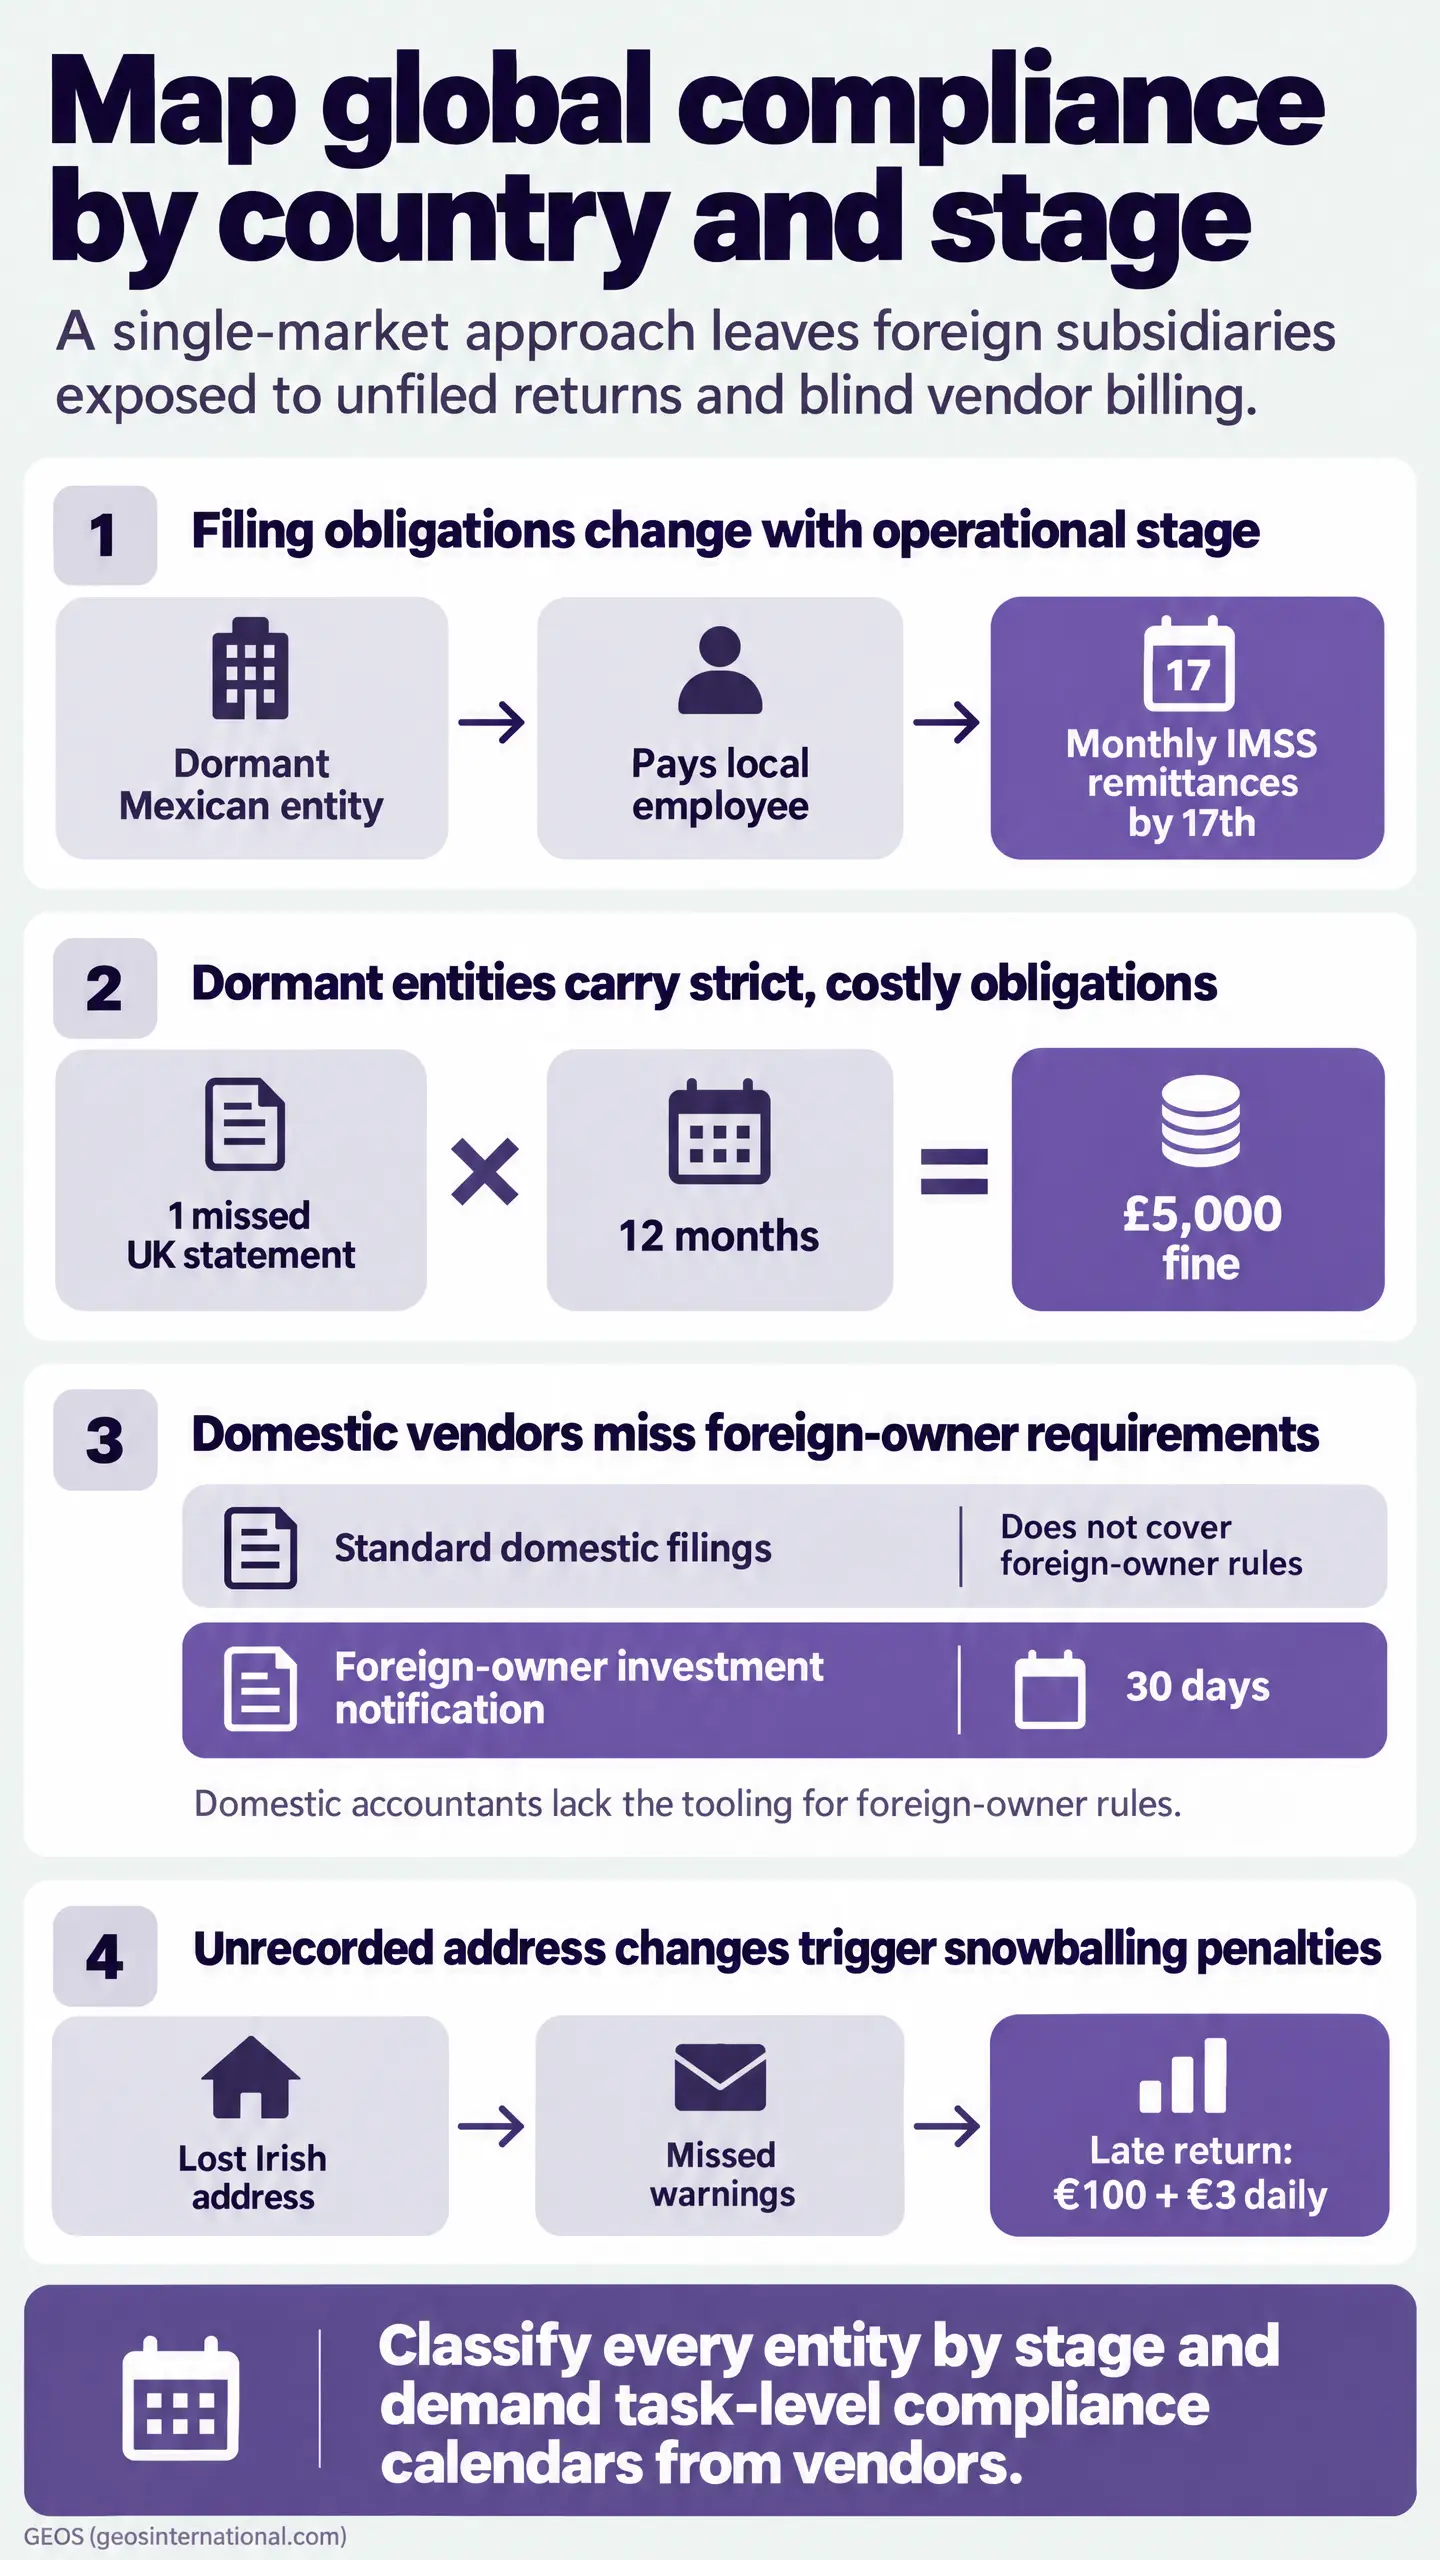
- A dormant UK company must file a confirmation statement every 12 months to avoid fines up to £5,000 and forced strike-off by Companies House.
- UK Companies House requires six to seven million directors and people with significant control to verify their identity by mid-November 2026, with verification windows opening on their birth month.
- Foreign owners establishing a new Canadian business must file an Investment Canada Act notification within 30 days of implementation, a requirement frequently missed by domestic accountants.
- A Mexican subsidiary shifts to a monthly compliance cadence the day it pays a local employee, requiring social security remittances to IMSS by the 17th of the following month.
- The Irish Companies Registration Office requires a physical registered address and penalizes late annual returns starting at €100 plus €3 daily, which can forfeit a company’s audit exemption.
- Peru’s General Companies Law mandates at least two shareholders and allows a six-month recovery period to restore this minimum before dissolving an entity by operation of law.
- Global entity compliance systems must require local vendors to upload government filing confirmations to close assigned tasks, eliminating blind billing for dormant subsidiaries.
How Do Global Corporate Filings Vary by Jurisdiction and Operational Activity?
Every jurisdiction has a corporate secretarial function. It is the person or firm responsible for keeping the lights on from a compliance perspective: lodging the annual corporate return, maintaining the registers, processing a new director or a change in shareholding. In some countries that must be a named natural person. In most it is more of a spiritual role, and inside a scale-up it lands on whoever is most organized.
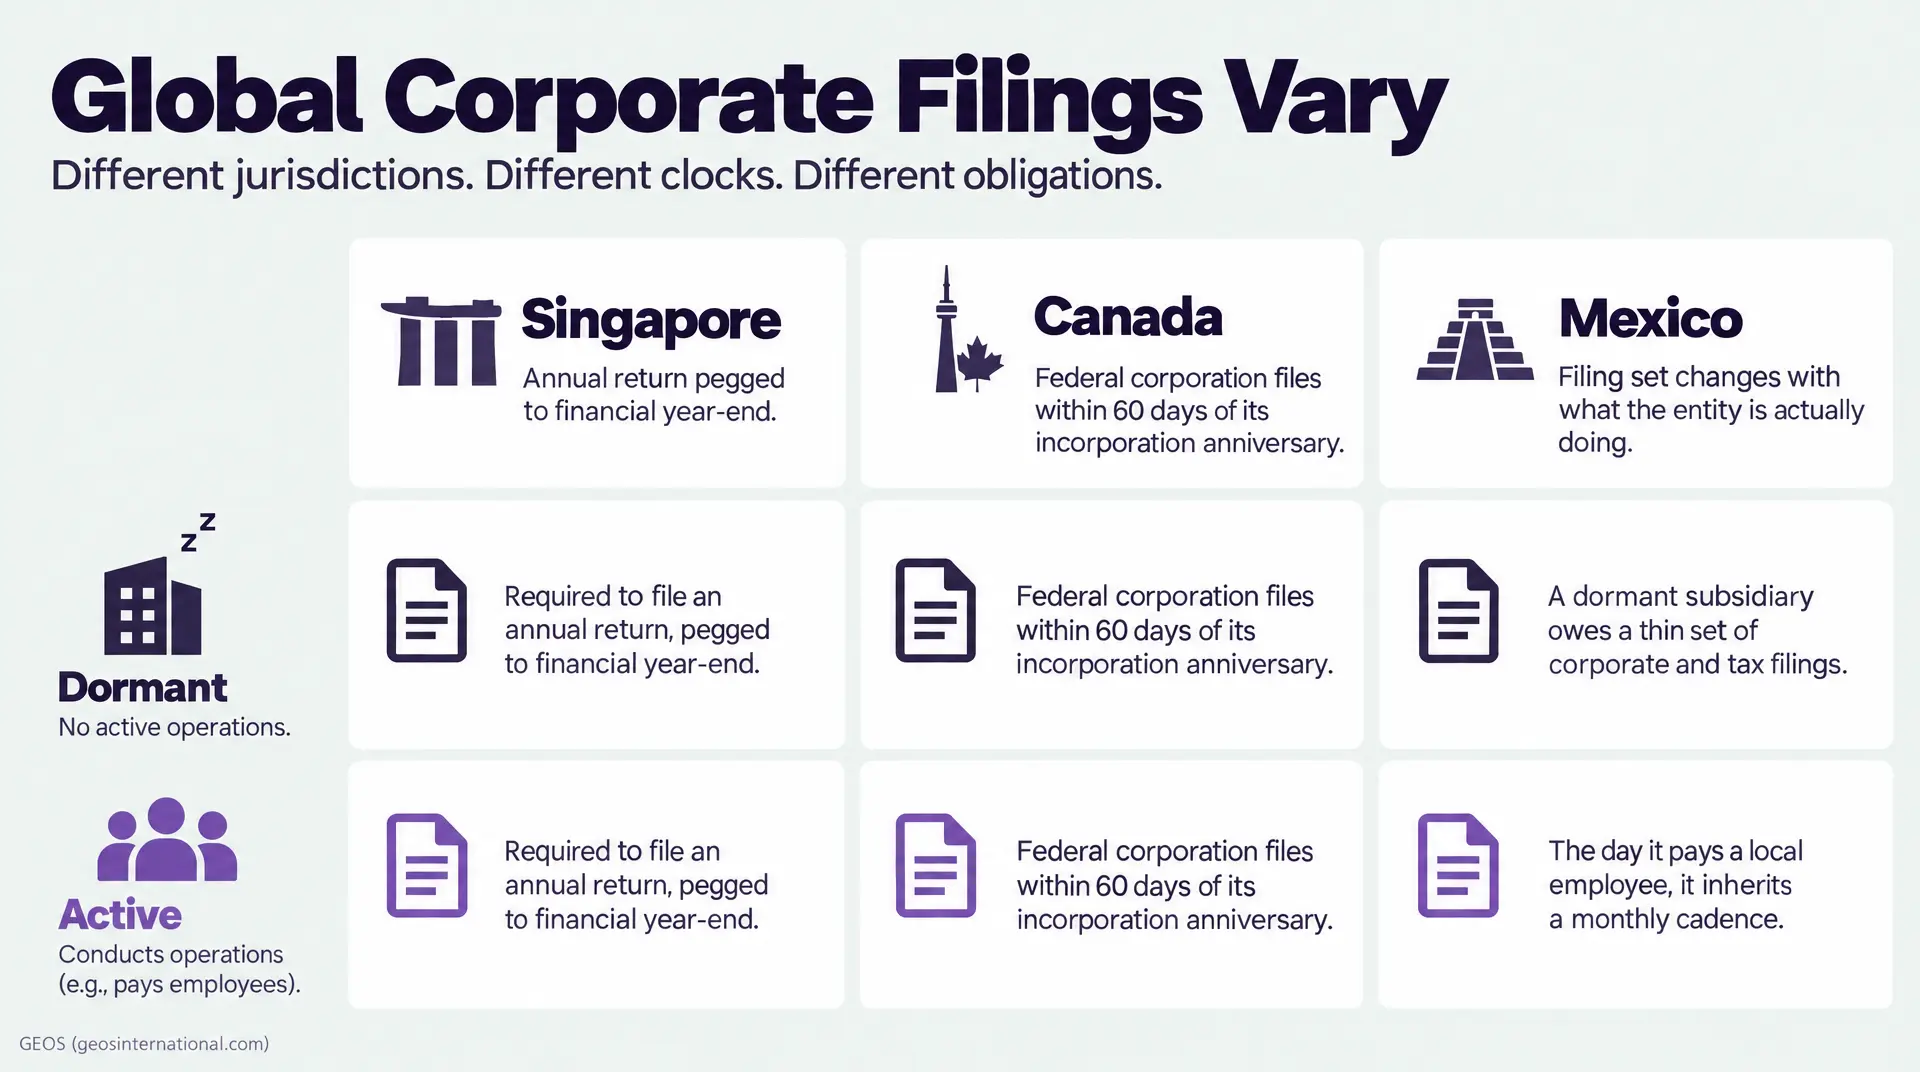
The first layer of variance is the one everyone expects. Mexico has a completely different set of annual filings than Singapore, which is different again from Canada, and even the due-date logic differs. Singapore pegs the annual return to financial year-end, seven months after year-end for a non-listed company. A federal Canadian corporation files within 60 days of its incorporation anniversary, separately from its tax return.
The second layer is the one that catches teams off guard. Inside one country, the filing set changes with what the entity is actually doing. A dormant Mexican subsidiary owes a thin set of corporate and tax filings. The day it pays a local employee, it inherits a monthly cadence, with social security contributions remitted to IMSS by the 17th of the following month. Once it recognizes revenue, the revenue-side filings arrive on top, and the annual return to SAT, due March 31, 2026 for 2025 filers in the General Regime, stops being a near-empty submission.
Across 10 or 15 entities you are managing a matrix, and until each entity is placed by country and stage you cannot say whether its filings are covered.
What Are the Corporate Compliance Obligations and Vendor Billing Risks for Dormant Foreign Entities?
The first platform dedicated to streamlining entity setup and management.
Dormant is a stage with its own obligations. A UK company that has never traded still owes at least one confirmation statement every 12 months, and Companies House can fine it up to £5,000 and strike it off for missing one.
What dormant should mean is a shorter list: no payroll remittances, no social contributions, no VAT returns. Still one of the most common things we find when onboarding an existing entity is a firm sending a generic level of annual billings, priced as if the entity were fully operational, for a subsidiary set up ahead of a launch that slipped and has sat idle since. Nobody told the vendor the stage had changed, and the vendor never asked. I have seen premium invoices from legacy firms with a single line item reading “corporate compliance” and no breakdown of the work behind it, which leaves an operations team paying for insurance and putting blind trust into the local vendors.
A US-based company came to us with three largely dormant subsidiaries, two in Latin America and one in APAC, paying significant monthly fees to a partner that could not say what compliance work was actually being performed. We mapped the real task list for a dormant entity in each country, audited it with local partners, and the gap was obvious enough that they switched immediately.
The fix is classification. Sort every entity by stage, then require a task-level compliance calendar from each vendor that reflects that stage. A firm that cannot produce one is billing from a template, and the template is usually the operational one.
What Foreign-Owner Specific Compliance Filings Are Commonly Missed by Domestic Accountants?
The second failure mode runs the opposite way: required work is going undone because the local vendor does not know it exists. These obligations apply only because the owner is foreign, and a firm built on domestic clients has had no reason to learn them.
What Are the Investment Canada Act Notification Requirements for Foreign-Owned Canadian Subsidiaries?
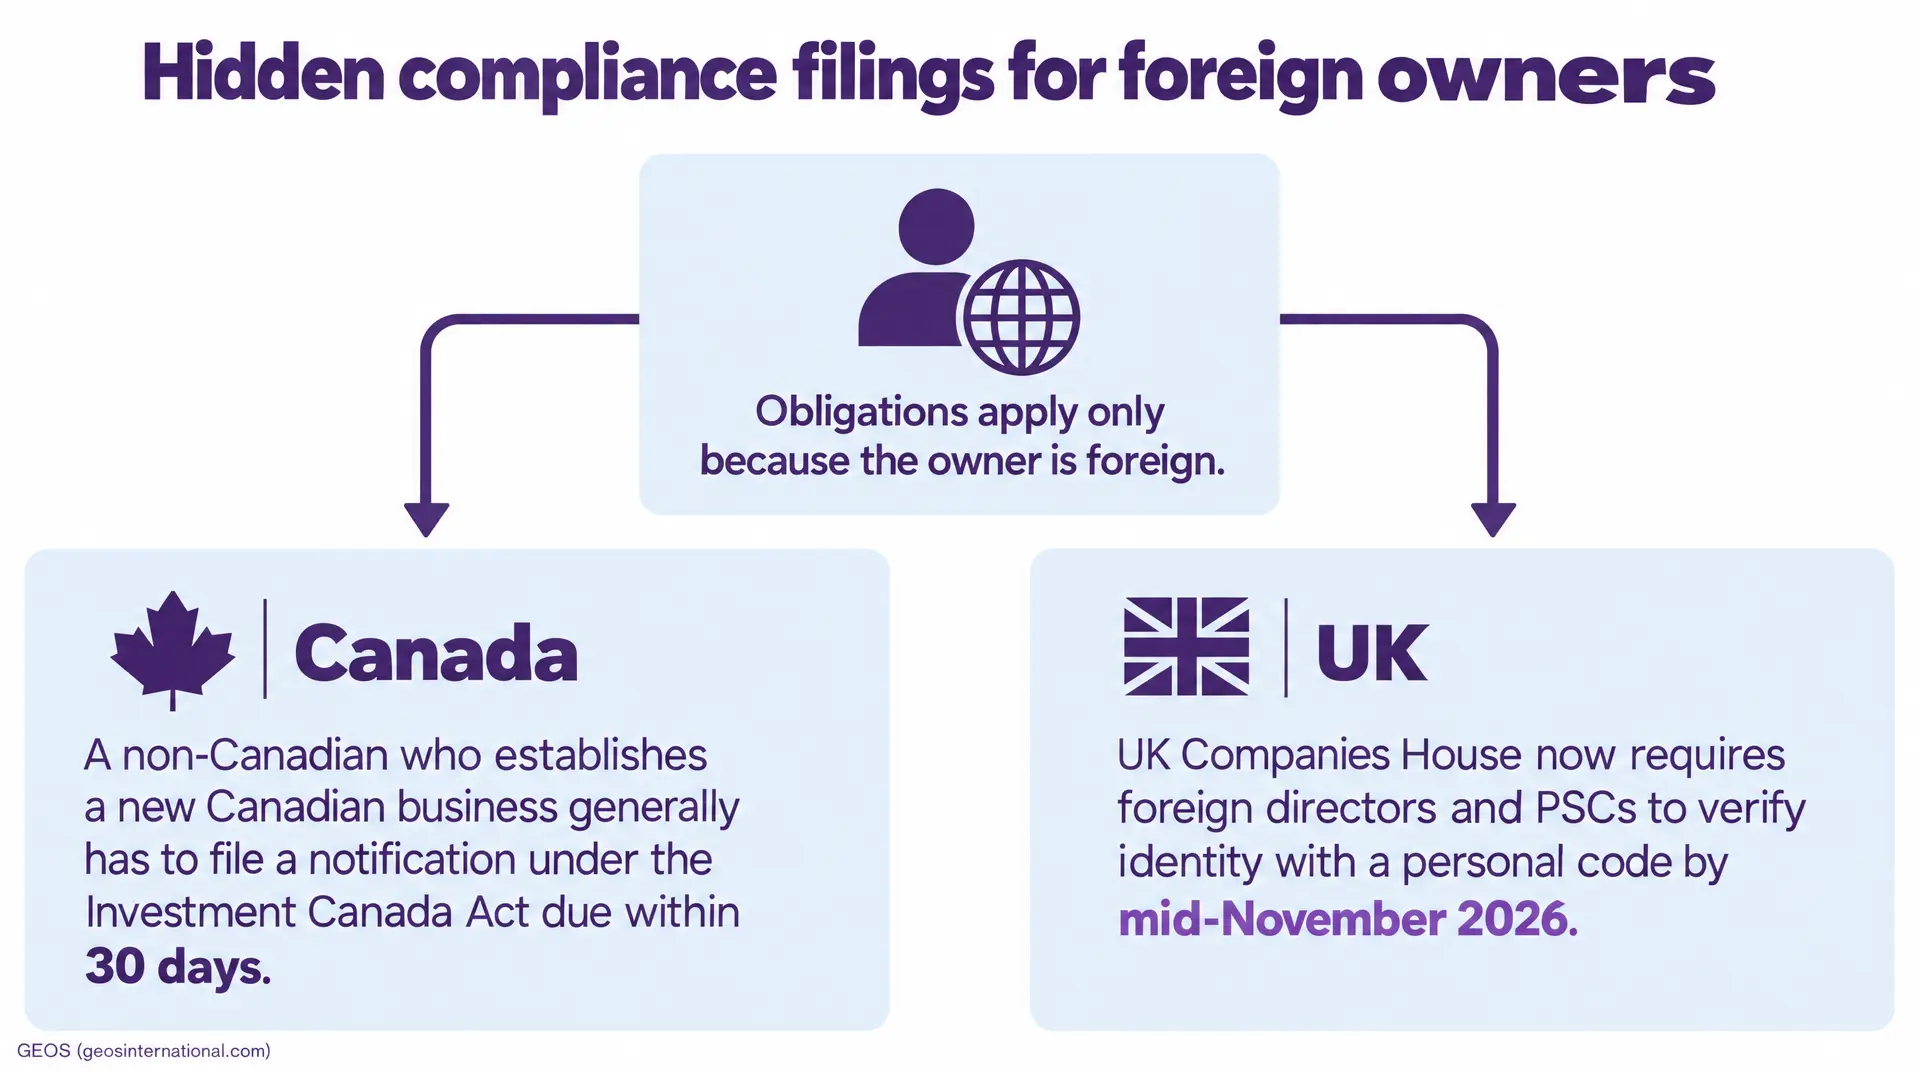
A Canadian-owned company has nothing to file under the Investment Canada Act. A non-Canadian who establishes a new Canadian business, or acquires control of one, generally has to file a notification or review application, and a notification for a non-reviewable investment is due within 30 days after implementation. It is a one-time obligation triggered by a foreigner setting up the entity, which is why a domestic accountant may never have seen one. We have onboarded foreign-owned Canadian subsidiaries where the accountant had never heard of it, and the client learned the notification had simply never been filed since incorporation years earlier.
What Are the 2026 UK Companies House Identity Verification Requirements for Foreign Directors?
The UK is producing a 2026 version of the same gap. Companies House now requires directors and people with significant control to verify their identity and hold a personal code for each company role. The agency estimates six to seven million individuals will need to verify by mid-November 2026. A PSC who is not also a director has 14 days to provide their code, and for an existing PSC that window opens on the first day of their birth month. No UK accountant’s standard calendar tracks the birth month of a founder in Toronto or Austin who sits on the PSC register.
I want to be fair to local accountants, because I do not believe this is a black box by design. Most single-market firms serve domestic companies and lack the foreign-client experience and tooling to surface requirements that only exist for foreign-owned entities. This comes down to not knowing what you don’t know in every jurisdiction, and it applies to the vendor as much as to you. Your protection is a per-country baseline of foreign-owner requirements that each vendor gets measured against.
How Do Unrecorded Structural and Address Changes Cause Rejected Global Corporate Filings?
The hardest failure to see coming is structural. An entity’s shareholders or directors change, nobody updates the record, and the next annual filing bounces because the entity no longer matches what the registry expects.
A client’s Peruvian subsidiary ran into this. Peru’s General Companies Law requires at least two shareholders, and the second shareholder on this entity was a former employee who had left. Peru allows six months to restore the minimum before the company is dissolved by operation of law, so it was recoverable, but nobody internally had connected the departure to the cap table. We drafted and submitted the documentation to appoint a replacement shareholder and the entity returned to good standing. A system of record tying shareholder attributes to a compliance flag would have raised this the day the employee resigned.
Catching these changes early takes a mapped system of record, local professionals who catch wind of things on the ground, and control of the registered address. Ireland shows why that last piece matters: the CRO requires a registered office to be a physical address, not a P.O. Box, and any notice sent to the address on record is deemed delivered even if the company has moved. If your Irish subsidiary’s registered office is a serviced desk given up two leases ago, the warning letters are going to nobody. The late annual return fee starts at €100 and adds €3 per day, and persistent lateness can cost the company its audit exemption. A return that should have cost nothing to file ends up forcing a statutory audit.
A centralized compliance partner holding the registered address collects that mail, scans it onto the platform, and routes it to a task. That is the earliest warning you can build for changes nobody flagged internally.
Why Does Global Corporate Compliance Require Local Partner Oversight Alongside Software Calendars?
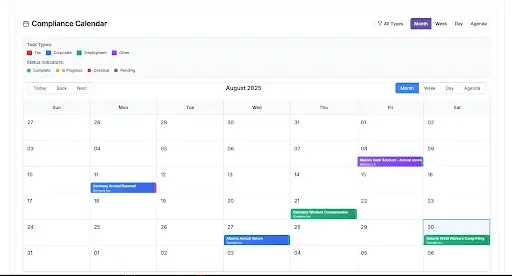
Deadlines are fixed. The responsiveness of the people who help you meet them is not. Communication with local partners in Spain predictably drops off through August and again in December, so anything needing a Spanish sign-off in those windows should be treated as due beforehand. The reverse also holds, and it is why I would never run a compliance program on software alone. When a client expanding into India moved employees off a global payroll provider they had used as a band-aid during setup, our local tax partner flagged the specific steps required to make the subsidiary’s provident fund account whole, since contributions normally remitted through a monthly electronic challan due by the 15th had been made in a roundabout way. No notification engine would have caught that.
How Should Centralized Systems of Record Be Structured for Global Entity Compliance in 2026?
Going into 2026, this is the model I would run.
Start with an intake per entity that ends in a mapped page: attributes, documents, registrations, and a compliance calendar built from where that entity sits in the country-and-stage matrix. When we onboard an existing subsidiary, roughly 90 to 95% of its tasks come straight from our pre-mapped baseline for that country. The remaining 5 to 10% are specific to the client, and that is where the risk hides. An extra-provincial registration in Canada, with its own agent for service and its own annual filing, because a salesperson was hired in British Columbia. That kind of task surfaces only by asking the client and the existing vendors directly.
Assign every task to a named responsible party and make completion contingent on evidence. Annual compliance is divvied up to multiple responsible parties: tax to the tax partner, payroll filings to the payroll provider, corporate returns to whoever holds the corp sec role. Each assigned task triggers an automated notification, and closing it requires uploading the receipt or filing confirmation. That one rule ends the practice of vendors who blindly bill for tasks that are arbitrarily maybe being done or maybe not.
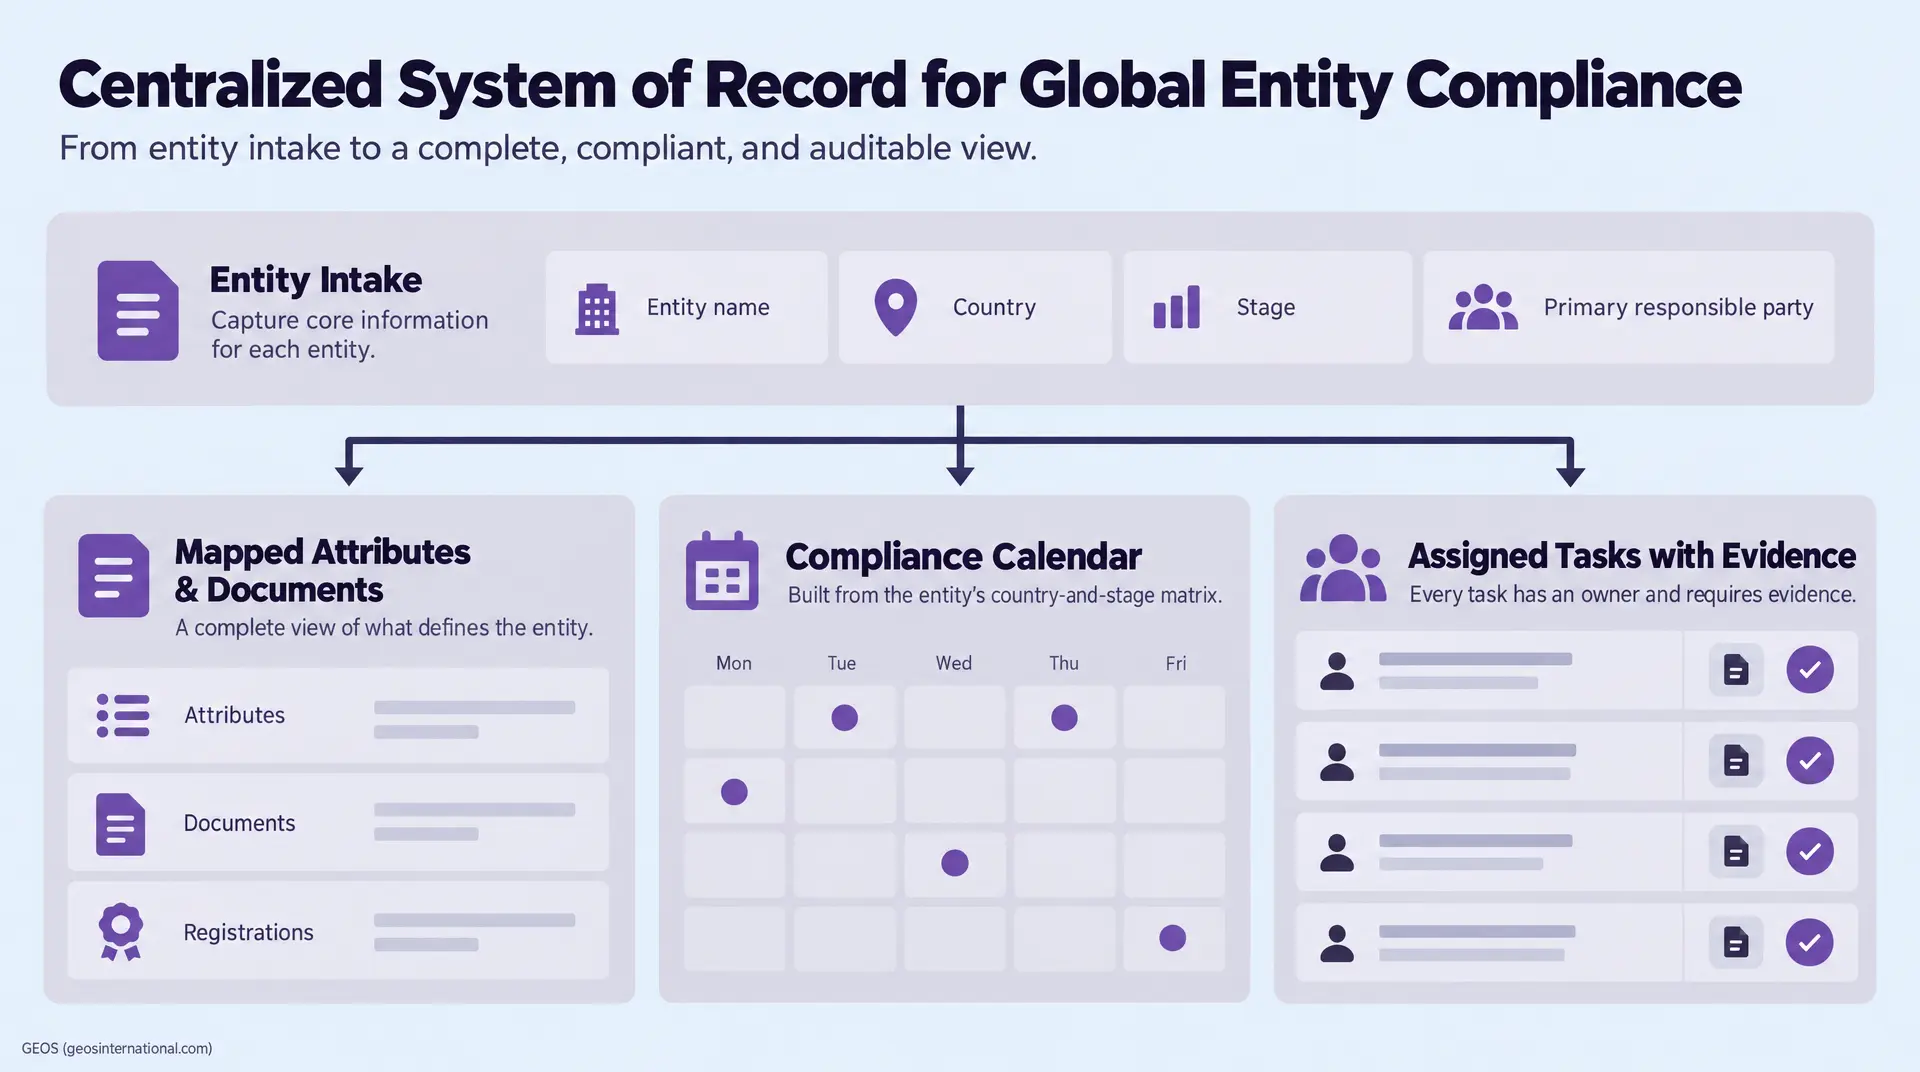
Consolidate visibility without ripping out what works. I do not think it is realistic to find one provider that handles tax, legal, and payroll well across dozens of countries. Keep the local firms that perform and plug them into the platform, and replace the ones that do not.
One client shows where vendor sprawl ends. A company with more than 30 entities had lost visibility into compliance costs entirely, because local firms were invoicing each subsidiary directly and nothing rolled up. Untangling years of backdated work and unverified invoices required a dedicated full-time compliance hire working alongside us. Managing independent local resources across a dozen countries becomes two or three full-time jobs just processing invoices and chasing actions.
How Do Companies Audit Global Entity Compliance to Establish a Baseline Inventory?
Start with the inventory. Classify every entity by country and stage, ask each vendor for a task-level calendar that reflects it, and confirm who physically receives government mail for each one. Everything else follows from that, and I would rather see a B-plus version running this month than an A-plus version next quarter.
Managing a global footprint without it is playing with a blindfold on, with a different vendor shouting directions from each country. Once the variance is less mysterious and more mapped out, what is missing becomes visible, and good standing becomes something you can track against a launch date like any other dependency.
Frequently Asked Questions
How do missed annual filings impact a scale-up’s M&A or funding rounds?
Missed filings derail due diligence immediately. A dormant entity failing to lodge returns doesn’t just incur fines – like Ireland’s late fees accumulating up to €1,200 – it loses good standing. Acquirers will freeze transactions until the legal plumbing is remediated, turning an administrative oversight into a blocked funding round.
What is the immediate operational cost of missing a foreign subsidiary’s filing deadline?
The financial penalty is measurable, but operational freezes are fatal. Singapore’s ACRA enforces a penalty up to S$600. More critically, local banks freeze subsidiary accounts when good standing is lost, instantly paralyzing your payroll.
Can we suspend annual filings if a planned international market launch is indefinitely delayed?
No. Registries do not recognize operational pauses. Even if entry stalls, a federal Canadian corporation must file within 60 days of its anniversary. You cannot press pause. You must either maintain the dormant matrix or dissolve the entity.
How do evolving identity regulations threaten routine annual filing deadlines?
Global registries are aggressively tying entity standing to individual verification. For example, the UK estimates 6 to 7 million individuals must verify their identity by mid-November 2026. If foreign directors or PSCs miss these personal compliance windows, the entity’s routine corporate filings will systematically bounce.
Does filing the local corporate tax return satisfy the subsidiary’s annual filing requirement?
Never conflate tax obligations with corporate registry maintenance. They are distinct operational streams governed by different authorities. In Canada, the corporate annual return is legally separate from the tax return. Assuming your accounting partner’s tax filing automatically keeps the entity in good standing is a common, disruptive failure.